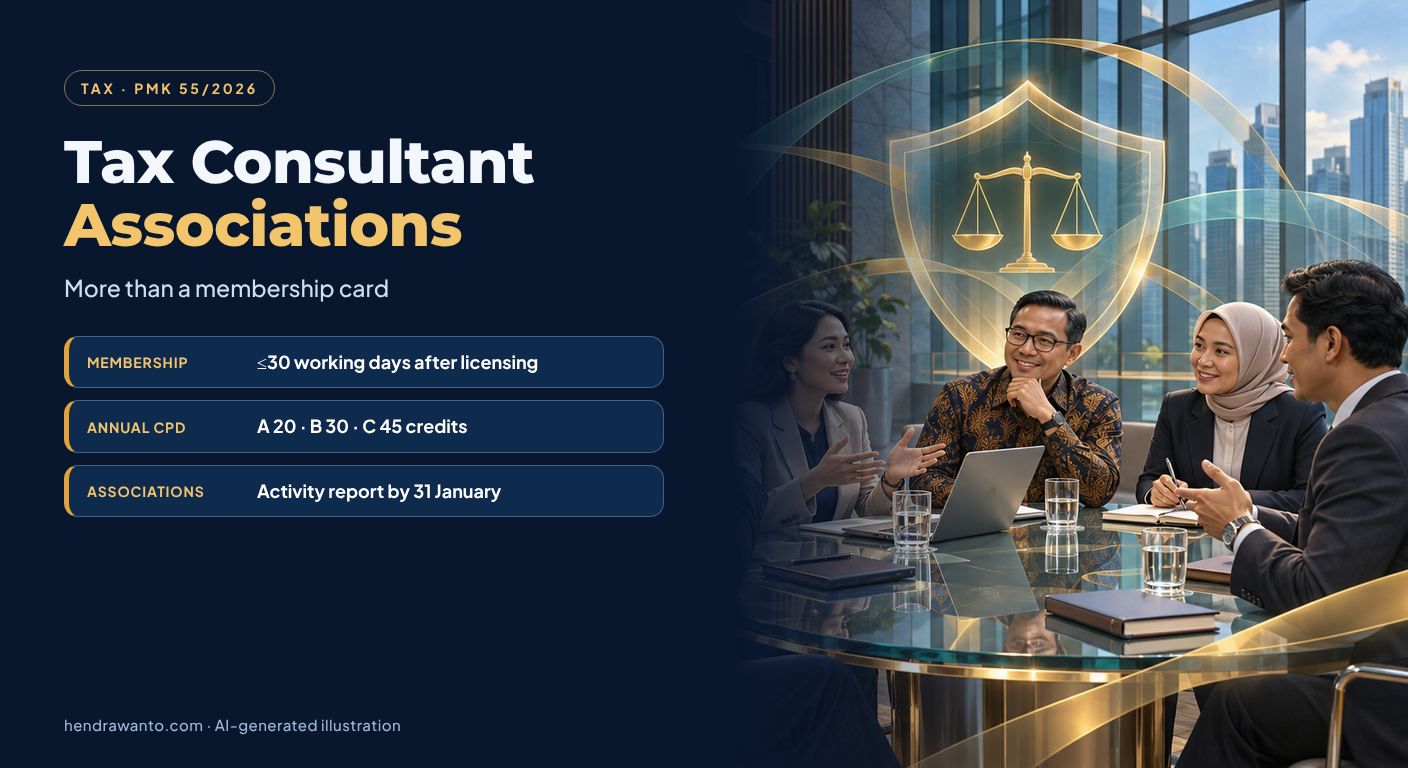
When choosing a tax consultant, a professional association membership card is often the first thing shown. The card helps trace an affiliation, but the check is not finished: is the association registered, does the person hold the right licence, and how is professional compliance maintained?
For aspiring consultants the question is different: after passing Indonesia's Tax Competency Test (UKP), what role does an association play? Does membership grant the right to practise? The answer requires separating competence, the professional exam, licensing, and membership. The main reference is Minister of Finance Regulation PMK 55 of 2026, effective since 24 August 2026. This article covers association governance and members' duties, not a popularity contest between organisations.
Separate the Organisation's Standing From the Individual's
PMK 55/2026 defines a Tax Consultant Association as a national organisation for the tax consulting profession. Article 31 requires associations to be registered with the Ministry of Finance. A deed of incorporation is only one requirement, not full proof of registered status.
| What to check | Evidence and meaning |
|---|---|
| Legal entity | Deed and approval; proves how the organisation was formed. |
| Registered association | Registration with the Ministry of Finance; determines its standing under the PMK. |
| Individual membership | Confirmation or membership documents from the association. |
| Authority to practise | Tax Consultant Licence with its classification and status; checked separately. |
Note also who the Director General is. Under this PMK, tax consultant licensing is handled by the Directorate General of Financial Sector Stability and Development (DJSPSK) on behalf of the Minister, not the Directorate General of Taxes. Do not rely on old service guides.
Four Associations Listed on the Government Portal
As of 11 November 2026, the FAQ on the Ministry of Finance SIKOP portal lists four associations:
| Acronym | Organisation |
|---|---|
| IKPI | Ikatan Konsultan Pajak Indonesia |
| AKP2I | Asosiasi Konsultan Pajak Publik Indonesia |
| PERKOPPI | Perkumpulan Konsultan Praktisi Perpajakan Indonesia |
| P3KPI | Perkumpulan Praktisi dan Profesi Konsultan Pajak Indonesia |
Article 60(c) keeps the registration of associations registered under the old rules. However, SIKOP still carries some old licensing guidance. Use the list as a starting point and confirm current status with the authority. The order is not a quality ranking.
On the institutional side, IKPI reported on 3 October 2026 that the four associations agreed to nominate the chairs of IKPI and AKP2I as association representatives on the Committee for Strengthening Tax Consultant Professionalism. That is a nomination, not an appointment.
What Should an Association Do?
The new framework links associations to the code of ethics, practice standards, continuing professional development (PPL), the professional exam, and member data. Under Article 31(3), registration requires:
- legal-entity status, articles of association and bylaws, and a tax ID (NPWP);
- a CPD programme, a code of ethics, and practice standards;
- an information system holding member and member-compliance data.
An association's quality can therefore be judged by evidence: relevant learning programmes, easy-to-find ethics documents, up-to-date member data, and traceable complaint handling. These are the author's practical criteria, not a government ranking. Networking helps, but the greater value shows when the organisation helps members make the right call in hard cases: requests to engineer outcomes, conflicts of interest, or work outside their licence.
Associations, the UKP, and the Professional Exam
BPPK distinguishes three documents: the SKK (competency certificate), the association's professional exam certificate, and the Tax Consultant Licence. The first two are licence requirements, not substitutes for the licence decision. See PMK 55/2026: Passed the UKP, Now What?
Under Article 32, associations hold the professional exam following the Committee's policy, and successful candidates receive a certificate from the association. Syllabus, schedule, pass criteria, and fees follow official notices; the UKP pass mark does not automatically apply. Article 61 requires the professional exam to be held by 31 December 2026 at the latest. That is a regulatory deadline, not an automatic schedule for every association.
Membership Has a Deadline and Sanctions
PMK 55/2026 reverses the old order. Association membership is no longer a prerequisite for the licence, but it must be in place within 30 working days after the licence is obtained (Article 25(1)). A consultant who resigns from an association must rejoin a Tax Consultant Association within 30 working days of resigning (Article 25(2)). Note the unit: working days, not calendar days.
When switching associations, record the effective date, obtain confirmation of acceptance, and keep the membership documents.
Plan CPD Rather Than Chasing It Before the Deadline
Article 26 sets minimum annual CPD credits (SKP) per licence classification. Structured credits are part of the total, so the two figures are not added together.
CPD may be provided by the Managing Unit, associations, or parties designated by the Committee. Attending one seminar does not necessarily meet the full requirement; check how activities are recognised and documented.
The CPD obligation starts in January of the year after the licence is issued, and the realisation report is due by 31 January of the following year. Example: a licence issued in November 2026 means CPD starts in January 2027, and the 2027 CPD report is due by 31 January 2028.
Associations Must Report Too
Article 33 requires associations to file an electronic annual activity report by 31 January of the following year. At minimum it covers professional exam and CPD results, other activities, complaints about suspected breaches of the code of ethics or practice standards and their follow-up, and the member list with current workplace and address data. Late filing draws a written warning.
This differs from the consultant's annual report (Article 28), due by 30 April of the following year. For consultants working at a tax consulting firm, the firm files the annual report. Sending documents to an association does not replace reporting to the authority.
Six Questions Before Choosing an Association
- Status: can its registration be confirmed with the authority?
- Learning: are the CPD calendar, credit recognition, and attendance records clear?
- Ethics: are the code of ethics, practice standards, and complaint channel available?
- Administration: are admissions, data updates, and transfers documented?
- Transparency: are dues, event fees, and service terms set out in writing?
- Relevance: do its content and support fit your work?
Ask for evidence, not promises. Claims of closeness to officials or guaranteed dispute outcomes are not a measure of professional competence. Technical decisions must rest on facts, documentation, and a testable legal basis.
Example: A Membership Card and an SKK Are Not Enough
A prospective service provider shows an association card and a Level C SKK. Before engaging them as a tax consultant, a company should ask for the licence, check its status and classification scope, and set the scope of work in writing. Membership and competence answer different questions from authority to practise. This is a fictional illustration, not a client case.
Conclusion
Tax consultant associations safeguard professional quality through learning, ethics, administration, and the professional exam. Choose an organisation based on verifiable status and demonstrable services. For clients, the check must reach the licence of the person engaged. For members, professional responsibility continues long after the card is issued.
References
- JDIH Ministry of Finance: PMK 55 of 2026 (enacted 22 July 2026; promulgated and effective 24 August 2026), especially Articles 25–26, 28, 31–33, 42, 60–61.
- Directorate General of Taxes: PMK 55/2026 text.
- Ministry of Finance SIKOP: association list FAQ.
- BPPK: tax consultant certification FAQ.
- IKPI, 3 October 2026: four associations' nomination agreement.
This article is general educational information, not legal advice for any specific case or an assessment of any particular association. Status, procedures, and operational notices should be rechecked on the date you act. The cover illustration was created with AI and does not depict any association's officers or meetings.