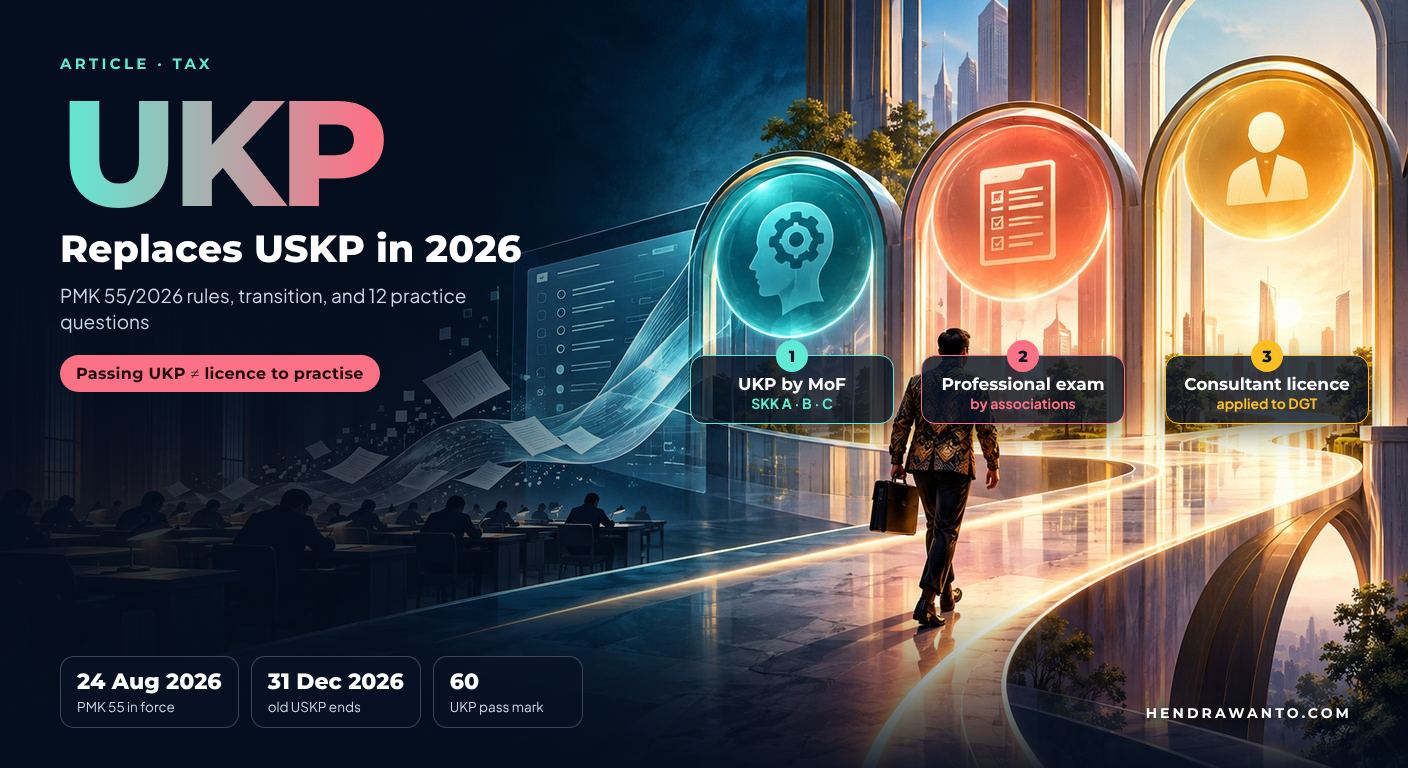
From 2026, the route to becoming a tax consultant in Indonesia no longer runs through the old Tax Consultant Certification Exam (USKP). PMK 55/2026 separates three stages: a competency test run by the Ministry of Finance, a professional exam run by associations, and the tax consultant licence. This article summarises the rules, the transition for holders of old USKP certificates, the first schedule, and 12 original practice questions.
Reference date: 27 October 2026. The official name is Uji Kompetensi Perpajakan (UKP), the Taxation Competency Test. Candidates who pass receive a Surat Keterangan Kompetensi (SKK), a competency certificate—not a licence to practise.
Passing the test is not the same as being licensed.
UKP by the Ministry
The Taxation Competency Test issues an SKK to candidates who pass.
Competency A, B, or CAssociation exam
A separate stage run by tax consultant associations (Article 32).
Not automatically part of the SKKLicence application
Filed electronically with the Minister through the Director General of Taxes, with education, experience, and personal requirements.
Tax Consultant Licence A, B, or CI hold an old USKP certificate. What changes?
The old certificate is recognised as an SKK for at most two years from its issue date, and can support a licence application until associations hold the professional exam. After that, old certificate holders must sit the professional exam to apply for a licence (Article 60 points f–g).
Does passing UKP C give a level C licence?
No. The competency test level and the licence classification are different things. A licence still requires an application and all Article 5 requirements, including the professional exam and work experience.
PMK 55/2026 Sets Out Three Separate Stages
Minister of Finance Regulation (PMK) 55 of 2026 on Tax Consultants and Other Parties Acting as Taxpayer Proxies was enacted on 22 July 2026, promulgated on 24 August 2026 (State Gazette 2026 No. 589), and took effect on promulgation. Article 61 point 2 revokes PMK 111/PMK.03/2014 as amended by PMK 175/PMK.01/2022. Its legal basis includes the General Tax Provisions Law and Law 4/2023 on Financial Sector Development and Strengthening as amended by Law 4/2026.
Stage 1 — Competency test and SKK (Articles 7–11)
The SKK is obtained by passing the taxation competency test run by the Competency Test Management Unit—the Ministry of Finance echelon I unit responsible for education, training, and certification (in practice, BPPK). Candidates must be Indonesian citizens whose NIK has been activated as an NPWP, and register electronically. The SKK is valid for three years from issue and can be renewed no earlier than one month before expiry through a refresher test.
- SKK AIndividuals, except individuals domiciled in tax treaty partner countries.
- SKK BIndividuals and entities, except among others foreign-investment companies (PMA), permanent establishments, and subjects domiciled in treaty partner countries.
- SKK CAll individuals and entities, including cross-border transactions.
Stage 2 — Professional exam by associations (Article 32)
The tax consultant professional exam is run by Tax Consultant Associations under policy set by the professionalism-strengthening committee. Article 61 point 1 requires the professional exam to be held no later than 31 December 2026.
Stage 3 — Tax Consultant Licence (Articles 3–5)
Anyone working as a tax consultant must hold a Tax Consultant Licence. Applications go electronically to the Minister through the Director General of Taxes. Requirements include: Indonesian citizenship; tax competence; passing an association's professional exam; at least a bachelor's degree or equivalent; tax work experience matching the licence class (at least one year for B and two years for C within the last three years); an NPWP; and not being an employee or official of a government body, state institution, or state- or region-owned enterprise. Passing UKP alone does not grant a licence to practise.
BPPK's official FAQ says UKP is not tiered: candidates may sit level B or C without first passing A. That does not automatically grant a level B or C licence, because the licence experience requirements still apply.
Transition Table: Old Certificates, SKK, and Licences
| Situation | Position as at 27 October 2026 | Reference |
|---|---|---|
| Old Practice Licence already issued | Remains valid as a Tax Consultant Licence. | Art. 60(a) |
| Licence, upgrade, or other service still in process before PMK took effect | Requirements follow the old rules; completion follows PMK 55. | Art. 60(b) |
| Registered associations or ongoing sanctions | Associations stay registered; warnings, suspensions, and revocations run until the sanction ends. | Art. 60(c)–(d) |
| Certification by the old USKP committee | May continue until 31 December 2026. This is a legal limit, not a promise of new sessions. | Art. 60(e) |
| Holding an old Tax Consultant Certificate | Recognised as an SKK for at most two years from the certificate's issue date (not from when PMK took effect). Usable for licence applications until associations hold the professional exam; after that, the exam is required. | Art. 60(f)–(g) |
| Association professional exam | Must be held no later than 31 December 2026. | Art. 61(1) |
| Passed only some old USKP subjects | The USKP Period III announcement limited resits to candidates listed in its annex. Conversion of partial USKP results to UKP is unconfirmed. | BPPK notice |
BPPK held USKP Period III 2026 as a resit for level A and B candidates listed in its announcement, with exams on 14–15 October 2026. Results were announced on Friday, 23 October 2026. Article 60(e) itself sets the legal end date for the old certification at 31 December 2026.
- 22 JulPMK 55/2026 enacted.
- 24 AugPMK 55/2026 promulgated and in force; PMK 111/2014 revoked.
- 14–15 OctUSKP Period III (level A and B resits).
- 16–20 OctRegistration for UKP periods 1–8 (PENG-7/PP/2026).
- 23 OctUSKP Period III results announced.
- 26–29 OctUKP periods 1–8: A (26), B (27), C (28), B (29).
- 12 NovPlanned announcement of UKP periods 1–8 results.
- 19 NovPlanned issue of SKKs.
- 31 DecDeadline for old USKP certification and for associations to hold the professional exam.
Registration, Exam Format, and Schedule
Registration is through the Kemenkeu Learning Center Certification portal using a Kemenkeu ID account. Uploads: national ID card, latest diploma, and a 4×6 photo on a white background. According to the official FAQ, UKP is free of charge.
The FAQ asks that all exam devices be ready at least 30 minutes before the exam starts. Questions are confidential and not shared with candidates, so any claim of "official leaked questions" should be rejected. Check your exam card, the Safe Exam Browser guide, and the latest instructions for your session.
Announcement PENG-7/PP/2026, issued by BPPK on 15 October 2026, sets out the first eight periods:
| Periods | Level | Date | Sessions (WIB) |
|---|---|---|---|
| 1 and 2 | A | Monday, 26 October 2026 | 08.00–11.30 and 13.00–16.30 |
| 3 and 4 | B | Tuesday, 27 October 2026 | 08.00–11.30 and 13.00–16.30 |
| 5 and 6 | C | Wednesday, 28 October 2026 | 08.00–11.30 and 13.00–16.30 |
| 7 and 8 | B | Thursday, 29 October 2026 | 08.00–11.30 and 13.00–16.30 |
The session window is not evidence of actual answering time. Results are scheduled for 12 November and SKK issue for 19 November 2026; PENG-7 also says UKP 2026 is planned for 40 periods. All three are the organiser's plans. For later periods, watch the official agenda.
Syllabus
BPPK links a document titled "Cakupan Materi Soal Uji Kompetensi Perpajakan 2026" on the UKP Candidate Info page. Press coverage groups the material as follows; treat the official document, not this summary, as the reference:
Twelve Original Practice Questions
The questions below are written entirely by the author and are not official UKP questions, answer keys, or predictions of the syllabus weighting. The A/B/C labels are only for grouping. Tap "Show answer" to reveal the explanation. Check the rules applicable on the transaction date for real cases.
- A · Individual return
Nia's tax year ends on 31 December 2026. The general deadline for her individual annual income tax return is…
- A. 31 January 2027
- B. 31 March 2027
- C. 30 April 2027
- D. 31 December 2027
Show answer
B. No later than three months after the end of the tax year, i.e. end of March. The four-month deadline (end of April) applies to corporate taxpayers.
- B · Corporate return
PT Awan uses a calendar financial year. The general deadline for its 2026 corporate annual return is…
- A. 31 January 2027
- B. 31 March 2027
- C. 30 April 2027
- D. 31 August 2027
Show answer
C. Four months after 31 December 2026 is 30 April 2027.
- A · Individual income tax
Rani received two withholding slips from two employers in one year. The correct step is…
- A. Report only the latest job
- B. Combine both incomes and take creditable withholding into account
- C. Ignore the slips
- D. No return needed
Show answer
B. The return combines all income for the year; Article 21 tax withheld that meets the requirements is a tax credit.
- A · Withholding
PT Sinar pays consulting fees to PT Bulan, a domestic company. The first article to test is…
- A. Article 21
- B. Article 23
- C. Article 26
- D. Stamp duty
Show answer
B. Consulting services to a domestic entity fall under Article 23 withholding; Article 26 applies to foreign recipients. The classification needs no rate assumption.
- A · VAT
Output VAT for a period is Rp18 million and fully creditable input VAT is Rp11 million. The difference is…
- A. Rp7 million payable
- B. Rp11 million
- C. Rp18 million
- D. Rp29 million
Show answer
A. Rp18 million − Rp11 million = Rp7 million VAT payable. Tax amounts are given as facts, so no rate is assumed.
- A · Input VAT credit
Input VAT was not credited in the period the invoice was issued. Is it automatically lost?
- A. Yes
- B. Not necessarily; it may still be credited within the next three tax periods if conditions are met
- C. Only after five years
- D. It becomes output VAT
Show answer
B. Article 9(9) of the VAT Law allows crediting within up to three subsequent tax periods subject to conditions. In real cases, check documents, expense treatment, and audit status.
- A · Stamp duty
The parties sign an electronic agreement as evidence. Which statement is correct?
- A. Always exempt from stamp duty
- B. It can be a stamp duty object
- C. Automatically subject to Article 21
- D. Not valid as a document
Show answer
B. Law 10/2020 on Stamp Duty covers electronic documents; the type and purpose of the document matter, not paper as a medium.
- A · Tax collection
A tax debt is unpaid and an officer wants to seize assets immediately. What should be checked?
- A. The invoice colour
- B. The warning/distress warrant stages and seizure requirements
- C. Social media followers
- D. Competitors' turnover
Show answer
B. Non-payment alone does not meet every precondition for seizure. The sequence and conditions are set by the law on tax collection by distress warrant.
- B · Fiscal reconciliation
A company books a shareholder's personal holiday of Rp40 million as a business expense. If unrelated to the business, the fiscal correction is…
- A. Positive Rp40 million
- B. Negative Rp40 million
- C. Tax credit Rp40 million
- D. No correction
Show answer
A. Personal expenses of shareholders are not deductible (Article 9 of the Income Tax Law). Adding it back raises taxable income by Rp40 million; a possible disguised dividend should also be considered.
- C · International tax
Royalties are paid to a foreign company that verbally claims treaty benefits. The correct step is…
- A. Apply the claimed rate immediately
- B. Check Article 26, recipient eligibility, proof of residence, and treaty procedures
- C. Treat it as tax-free
- D. Use Article 21
Show answer
B. A verbal claim is not enough. Domestic rules (Article 26) are the starting point, followed by proof of residence, beneficial ownership, and treaty administrative conditions.
- Professional orientation
Dita passes UKP B and receives an SKK. Has she automatically passed the professional exam and become licensed?
- A. Yes
- B. No, they are separate stages
- C. Only for a month
- D. She only needs to pay stamp duty
Show answer
B. The SKK comes from UKP; the professional exam is run by associations; the licence requires an application and other conditions (Articles 3, 5, 7–11, 32 of PMK 55/2026).
- Pathway orientation
Raka wants to sit UKP C directly without A and B. Which statement is correct?
- A. Not allowed
- B. He may choose C, but a level C licence still has its own requirements
- C. He automatically gets a C licence
- D. UKP has no levels
Show answer
B. The FAQ says UKP is not tiered; Article 5 separates exam choice from licence requirements, including two years' work experience for a C licence.
Separate Legal Certainty from Organiser Plans
Conclusion
Start by deciding your goal: obtaining an SKK, using your old USKP transition rights, or applying for a licence to practise. They are linked but are not the same document or exam. For old certificate holders, the certificate issue date and the date associations start holding the professional exam are two different time markers. For new candidates, BPPK's official portal is where to check the next agenda and the current syllabus document.
Need corporate tax support or want to discuss your tax team's readiness? See our Corporate Tax Advisory service.
Official References
- DGT: PMK 55 of 2026 on Tax Consultants and Other Parties Acting as Taxpayer Proxies (in Indonesian)
- Ministry of Finance JDIH: PMK 55 of 2026
- BPPK: UKP Candidate Info and Certification FAQ
- Announcement PENG-7/PP/2026 on UKP periods 1–8 (DDTC reproduction)
- BPPK: USKP Period III 2026 results (23 October 2026)
- Law 7/2021 on Harmonisation of Tax Regulations and Law 10/2020 on Stamp Duty
This article is educational and is not legal advice or a guarantee of passing. Practice questions are written by the author and do not represent official UKP questions. Schedules and technical rules may change; always check BPPK's latest announcements and the full text of PMK 55/2026. The Indonesian version is the original text.