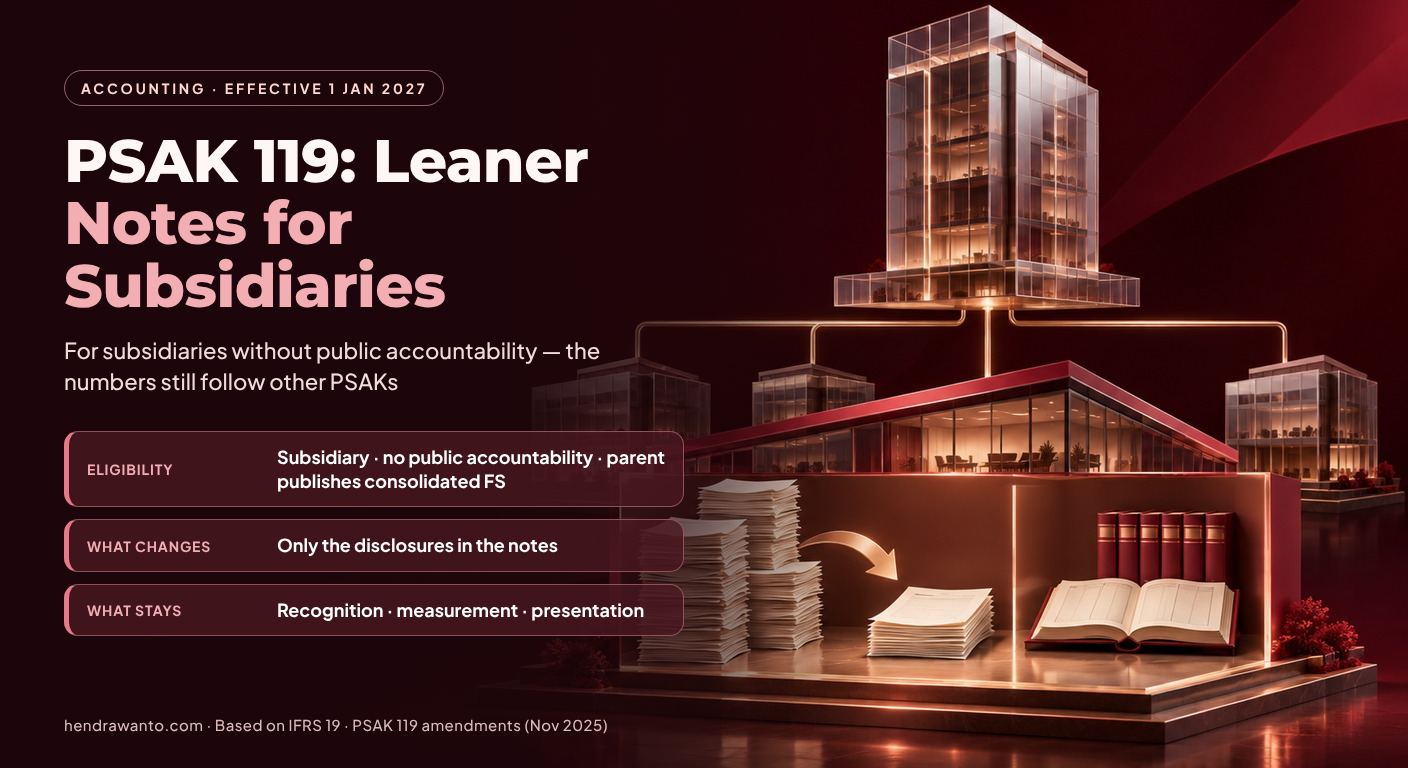
Subsidiary financial statements often face a dilemma. The group needs figures prepared under aligned accounting policies, yet the readers of a subsidiary's statements rarely need notes as extensive as those required by investors in a listed company. As a result, subsidiary accounting teams often prepare dozens of pages of notes whose information is already in the parent's consolidated statements.
PSAK 119 Subsidiaries without Public Accountability: Disclosures offers a middle path: reduced disclosure requirements for eligible subsidiaries, while recognition, measurement, and presentation continue to follow other PSAKs (Indonesian Financial Accounting Standards). According to the Institute of Indonesia Chartered Accountants (IAI), its Financial Accounting Standards Board (DSAK IAI) approved PSAK 119 on 27 August 2025. The standard is based on IFRS 19, issued by the IASB in May 2024, and applies to reporting periods beginning on or after 1 January 2027, with earlier application permitted.
Who Can Apply It?
PSAK 119 is optional, not mandatory. According to the IAI, it may be chosen by a subsidiary that has no public accountability and whose parent prepares consolidated financial statements available for public use under SAK Indonesia, SAK Internasional, or IFRS Accounting Standards. All three conditions must be met at once.
A subsidiary
A control relationship exists- Controlled by another entity
- Not a stand-alone private company
No public accountability
The entity itself, not the group- No debt or equity instruments traded, or being issued, in a public market
- Does not hold assets in a fiduciary capacity for a broad group of outsiders as a primary business
Parent reports publicly
Ultimate or intermediate parent- Consolidated financial statements available for public use
- Under SAK Indonesia, SAK Internasional, or IFRS
What about intermediate parents?
IFRS 19, on which PSAK 119 is based, requires an intermediate parent to assess its own eligibility, regardless of the public accountability of the group as a whole (paragraphs 9–10). The IAI's summary of the PSAK 119 amendments also mentions a change concerning intermediate parents and their separate financial statements. Because the summary is brief, read the final wording in SAK Online before deciding.
Is a specific statement required in the notes?
Yes. IFRS 19 paragraph 20 requires an explicit and unreserved statement of compliance, including a statement that the standard has been applied. Check the PSAK 119 equivalent and adjust the accounting policy wording.
Public accountability is assessed for the entity itself. Under IFRS 19 (paragraph 11), an entity has public accountability if its debt or equity instruments are traded in a public market or it is in the process of issuing them for trading in such a market, or if it holds assets in a fiduciary capacity for a broad group of outsiders as one of its primary businesses. Holding assets in a fiduciary capacity only incidentally to a primary business does not by itself create public accountability (paragraph 12). The final assessment still follows the PSAK 119 text and the sector regulations that apply in Indonesia.
Illustrative example. PT Induk publishes consolidated financial statements under SAK Indonesia. Its subsidiaries:
| Subsidiary | May it elect PSAK 119? |
|---|---|
| PT Anak Manufaktur: issues no securities and manages no third-party funds | Likely yes |
| PT Anak Finansial: has bonds listed on the stock exchange | No |
| PT Anak Bank: takes deposits from the public | No |
| PT Anak Asing: its foreign parent publishes IFRS consolidated statements | Likely yes |
Being a subsidiary of a listed company is not enough if the subsidiary itself has public accountability. Conversely, the parent does not have to be listed; what matters is that its consolidated statements are publicly available and prepared under a recognised framework. This example does not determine eligibility for any particular company.
What Changes, and What Does Not?
PSAK 119 changes only the disclosures in the notes to the financial statements. An entity that elects it applies the PSAK 119 disclosure requirements in place of the disclosure requirements of other PSAKs. For recognition, measurement, and presentation, however, it continues to apply the other PSAKs.
PSAK 119 is therefore not permission to change the measurement basis of assets, remove liabilities, or calculate profit differently. A subsidiary's figures must still match what the consolidation package needs. Nor is PSAK 119 a reason to drop additional information that users need to understand the effect of particular transactions or conditions.
PSAK 119 also differs from SAK Entitas Privat (SAK EP), the private entity framework. SAK EP, which replaced SAK ETAP from 1 January 2025, is a separate framework that also simplifies some recognition and measurement principles. See the SAK EP transition map.
| Aspect | Full SAK Indonesia | SAK Indonesia + PSAK 119 | SAK EP |
|---|---|---|---|
| Recognition & measurement | Full PSAKs | Full PSAKs (same) | Simplified for some topics |
| Disclosure | Full | Reduced under PSAK 119 | Under SAK EP |
| Main condition | — | Subsidiary; parent publishes consolidated statements | No public accountability |
| Consolidation package | Aligned | Aligned; no adjustments to figures | Adjustments needed if the parent uses SAK Indonesia/IFRS |
Why Do the 2025 Amendments Matter?
On 24 November 2025, DSAK IAI approved the Amendments to PSAK 119. They are based on the amendments to IFRS 19 issued by the IASB on 21 August 2025, and also take effect on 1 January 2027 with earlier application permitted. The May 2024 version of IFRS 19 covered IFRS requirements only up to February 2021; the amendments extend the reliefs to later changes. According to the IAI's summary, the amendments:
- change the provisions on application by an intermediate parent in its separate financial statements;
- remove disclosure objectives for supplier finance, lack of exchangeability, the Pillar Two model rules, classification and measurement of financial instruments, and non-current liabilities with covenants;
- reduce the disclosure requirements for supplier finance arrangements;
- remove material that is guidance rather than a disclosure requirement;
- replace the disclosure requirements for management-defined performance measures with a cross-reference to PSAK 118.
The implication: do not build a disclosure checklist from the original version of PSAK 119 alone. Use the standard together with its final amendments for the relevant period.
- IFRS 19 issuedThe IASB issues a disclosure standard for subsidiaries.
- IFRS 19 amendmentsReliefs extended to new standards issued since 2021.
- PSAK 119 approvedDSAK IAI adopts IFRS 19.
- PSAK 119 amendmentsIncluding a cross-reference to PSAK 118.
- Effective2027 financial statements; earlier application permitted.
The link with PSAK 118 matters for groups that are also preparing the new profit or loss format and management-defined performance measure disclosures from 2027. See PSAK 118: The New Profit or Loss Statement from 2027.
Four Preparation Steps for Business Groups
- MapControl relationships, public accountability status, and the parent's consolidated statements.
- CompareCurrent notes with the final PSAK 119 and its amendments, topic by topic.
- AlignFigures and policies stay the same as the consolidation package.
- ReviewWith the auditor, audit committee, lenders, and sector regulator.
1. Map potentially eligible entities. Document the control relationships, each entity's public accountability status at the end of the reporting period, and the framework and public availability of the parent's consolidated statements. This documentation also serves as evidence for the auditor.
2. Compare current notes with the final PSAK 119. Build a disclosure matrix by topic: retained, reduced, or no longer required. Do not assume every note can be removed.
3. Keep group figures and policies aligned. Reduced disclosures must not disrupt consolidation data. Detailed data no longer disclosed in the subsidiary's statements may still be needed in the reporting package to the parent.
4. Review with the auditor and audit committee before adoption. Consider the needs of report users, loan agreements that require particular disclosures, and sector regulations. From an audit perspective, the change in disclosure policy will be considered in assessing compliance with the reporting framework, including the wording of the compliance statement in the notes.
Conclusion
PSAK 119 is a more proportionate reporting option, not "lighter accounting" for every subsidiary. Its benefits arise when a group assesses eligibility correctly, uses the standard with its final amendments, and shortens the notes without losing important information. Ahead of 2027, the main task is not new journal entries but deciding who is eligible and which disclosures are still needed.
Need help assessing eligibility and building a disclosure matrix? See our Accounting & SAK Implementation service.
Official References
- IAI: Approval of PSAK 119 Subsidiaries without Public Accountability: Disclosures (in Indonesian)
- IAI: Approval of the Amendments to PSAK 119 (in Indonesian)
- IFRS Foundation: IFRS 19 Subsidiaries without Public Accountability: Disclosures
- IFRS Foundation: IFRS 19 key terms
This article is educational and is not accounting advice for any particular entity. Before applying it, read the full text of PSAK 119 and its amendments in SAK Online and the relevant regulatory requirements.